Indonesia is signaling that it wants to be more than a nickel story. Officials have identified eight mining blocks that the government says hold “large potential” for rare earth reserves, and the move is being framed as part of a wider push into supply chains linked to magnets, EV motors, wind turbines, and defense technology. But “identified blocks” are not the same as bankable reserves. Multiple sources stress this is still the earliest stage, where mapping, permitting, and policy design matter as much as geology. Rare earth projects can face long lead times because metallurgy is difficult, product specifications are strict, and separation capacity is often the bottleneck.
The institutional build-out is moving faster than the physical build-out. Indonesia’s Mineral Industry Agency was established in August 2025, yet it has issued no mining business permits for rare earth operations and does not oversee any commercial rare earth production. The state has also established a new enterprise, Perminas, tasked with extraction and processing, and it is already collaborating with state-controlled PT Timah on tin-slag, monazite, and rare earth element (REE) processing. Mamuju in West Sulawesi has been designated as the national downstream pilot site. At the same time, Indonesia has put in place a mandatory rare-earth screening program, and over 100 mineral shipments were delayed in July 2026, underscoring regulatory and processing gaps that still need to be solved.
Downstreaming Lessons From Nickel—and the China Trade-off
Indonesia’s rare earth strategy is explicitly modeled on its downstreaming doctrine: restrict raw ore exports, promote domestic refining, export processed intermediates, and then push further into manufacturing. The nickel record explains why policymakers think the template can work. Between 2015 and 2024, Indonesia went from producing 6% of the world’s nickel to over 60%. Yet the same sources warn that repositioning is not the same as upgrading. In the first half of 2025, 94% of Indonesian nickel exports went to China, and in January–May 2026, China received approximately 98% of Indonesia’s ferronickel exports. That concentration highlights a risk: downstreaming can mature under Chinese capital and technology, leaving Indonesia producing more while much of the know-how and margins remain elsewhere.
Rare earths raise the partner dilemma even more sharply. Indonesia is described as lacking refining capacity and relying on imports, while facing high capital and technological barriers. One assessment argues that the only timely, viable path to processing Indonesia’s rare earths runs through China, even as the United States, Japan, and others push for diversification away from concentrated supply chains. Indonesia has also confirmed to the US (in February 2026) that any export flexibility applies only to processed minerals, not raw ores, signaling the downstreaming agenda is non-negotiable. But if Chinese partners are selected for REE separation facilities, the resulting supply chains may face market-access constraints under US and EU critical minerals sourcing rules, making technology partner choice a pivotal near-term signal.
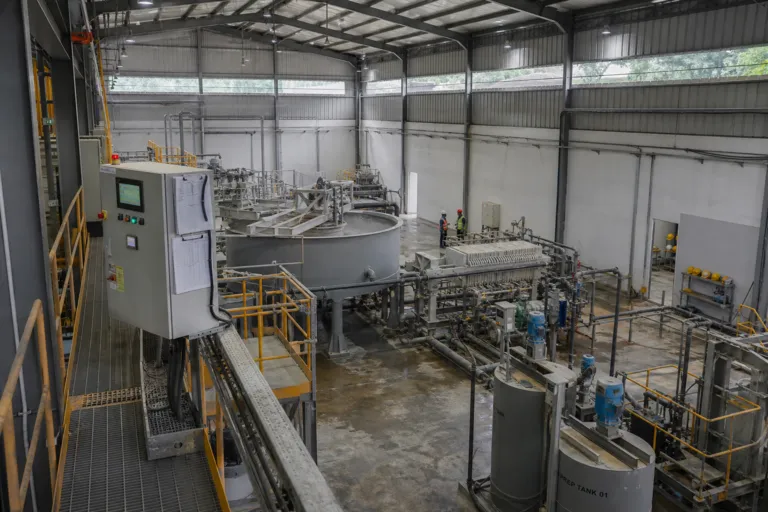
The ambition behind Indonesia rare earth processing is clear: pair upstream extraction with processing capacity that meets international standards and captures more domestic value. But sources caution that rare earths are not nickel. Low grades, complex mineralogy, radioactive residues, and difficult separation chemistry can undermine economics, while environmental, health, and energy costs must be weighed against industrial gains. Even Indonesia’s nickel boom came with trade-offs; one analysis notes the industry is overwhelmingly powered by captive coal plants, and most facilities produce between 57 and 70 tonnes of CO₂ per tonne of nickel. For rare earths, investors and manufacturers are watching whether Indonesia can convert early policy architecture—eight blocks, new agencies, pilot sites, and incentives—into reliable, scalable production without repeating past bottlenecks.
How advanced is Indonesia’s rare earth sector today?
What is Indonesia doing to move from mining into processing?
What does nickel reveal about downstreaming risks?
Why is partner choice so sensitive for rare earth separation?
What are the key hurdles for Indonesia’s rare earth processing push?