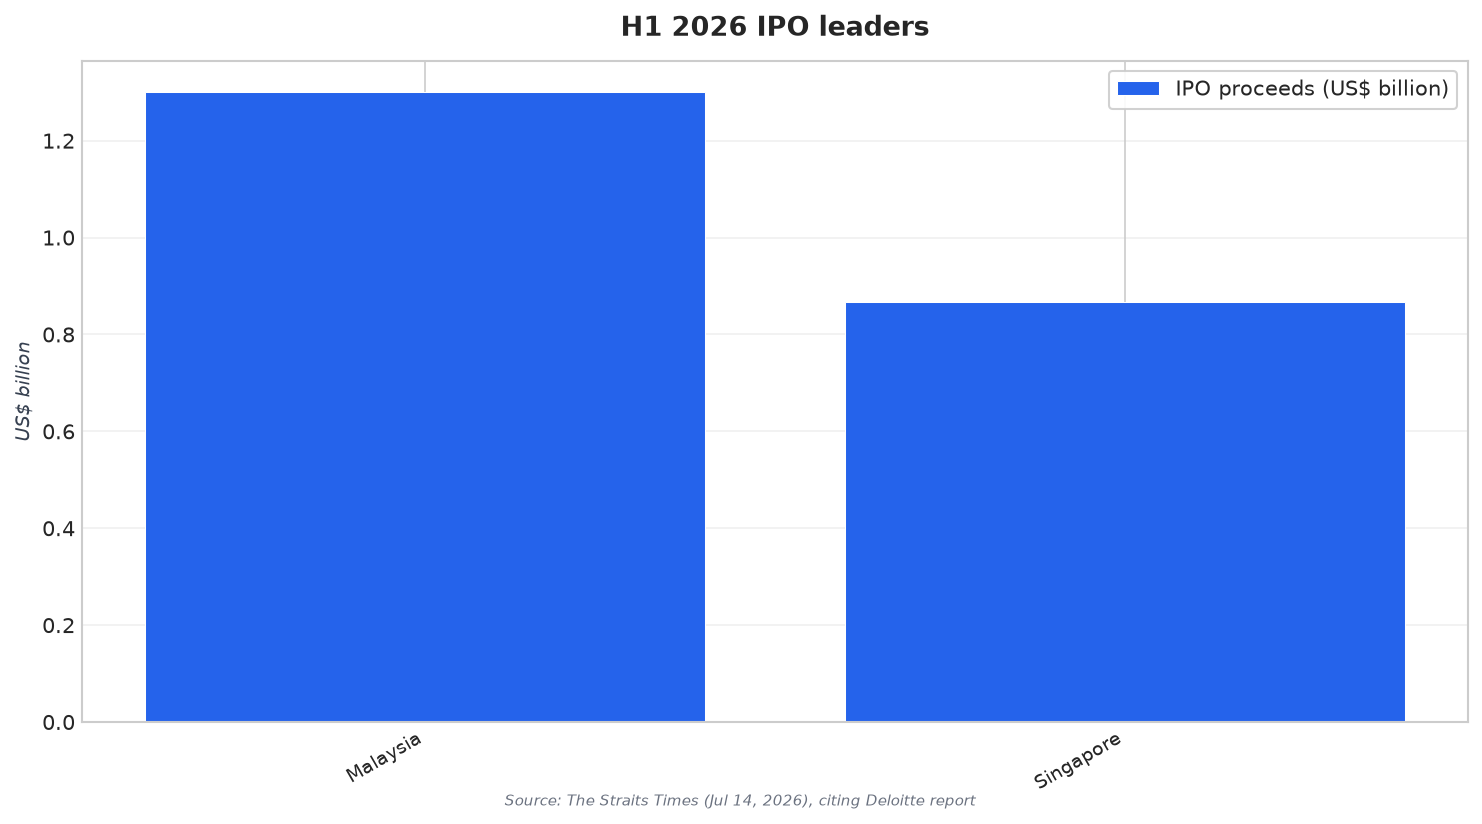
Malaysia held on to its position as Southeast Asia’s busiest IPO venue in the first half of 2026. A Deloitte report released on July 13 said Malaysia recorded 36 IPO listings, raising US$1.3 billion. The same snapshot showed Southeast Asia overall had 47 IPOs in the first half of 2026, with proceeds of more than US$3.07 billion and combined IPO market capitalisation of US$15.07 billion. Malaysia’s results stood out because the region’s volume moderated, but investor appetite concentrated on larger and higher-quality issuers.
Across Southeast Asia, the number of IPOs dipped 11% to 47 from 53 a year earlier, yet proceeds more than doubled to US$3.07 billion from US$1.41 billion. Deloitte also cited a sharp change in deal size, with the average IPO deal size rising 2.4 times to US$65 million from US$26 million in the first half of 2025. KLSE Screener reported that proceeds surged 117% year on year, while aggregate IPO market capitalisation rose 96% from US$7.7 billion. The narrative was consistent: fewer listings, larger transactions, and quality taking precedence over quantity.
Blockbusters and Pipelines: What’s Powering the Lead
Malaysia’s first-half leadership was supported by a standout mega listing. Sunway Healthcare Holdings raised about US$707 million and achieved a market capitalisation of US$4.13 billion. Deloitte and regional coverage described it as one of three Southeast Asian blockbuster IPOs that each raised more than US$500 million, alongside UI Boustead REIT in Singapore and Dien May Xanh Investment Joint Stock in Vietnam. Together, these three deals contributed about US$8.93 billion in market capitalisation. Deloitte’s Wong Kar Choon said Malaysia’s IPO market in 1H 2026 was “healthy and maturing,” moving from a volume-driven surge to a more balanced, quality-focused phase.
The broader pipeline story also matters. Deloitte cited a pipeline of more than 40 potential Malaysian listings for the remainder of 2026, reinforcing why the market remains closely watched by issuers and investors. In 2025, Malaysia also led on volume in a separate Deloitte update cited by Markets Group, with 48 listings raising US$1.1 billion, largely through the ACE Market, and commentary that Malaysia was on track to reach a target of 60 IPOs that year. Asia Lifestyle Magazine added that in H1 2025, Malaysia’s pipeline featured mid-cap offerings between RM 200 million and RM 800 million rather than reliance on a single blockbuster.
Regional comparisons underline the shape of the opportunity for issuers choosing where to list. In 1H 2026, Singapore placed second with five IPOs raising US$868 million, rebounding from just one listing in 1H 2025, with reforms and the Equity Market Development Programme cited as support. Vietnam returned from zero IPOs in 1H 2025 to four listings in 1H 2026, and KLSE Screener reported Vietnam recorded the region’s highest IPO market capitalisation at US$6.93 billion. In this context, Malaysia’s IPO market leadership is defined by both scale and consistency, while the region increasingly rewards fewer but bigger deals.
How did Malaysia rank in Southeast Asia’s IPO market in the first half of 2026?
What changed in Southeast Asia’s IPO market between 1H 2025 and 1H 2026?
Which deal was the standout Malaysian IPO in 1H 2026?
What supports continued Malaysia IPO market leadership beyond the first half?
How did Singapore and Vietnam compare with Malaysia in 1H 2026?